


Osmometers Market Size, Share, In-Depth Insights, Growth and Forecast 2026-2034
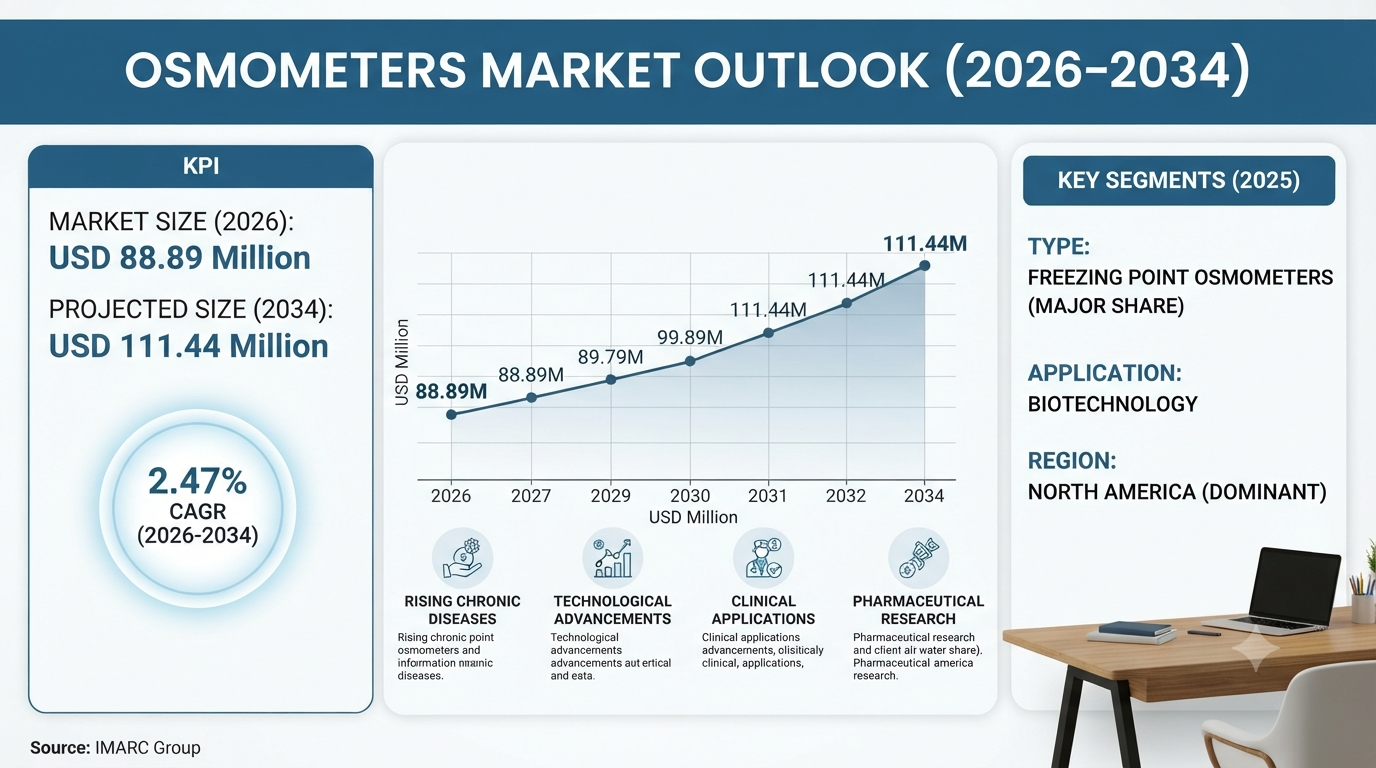
According to IMARC Group, the global osmometers market size reached USD 88.89 Million in 2025 and is projected to reach USD 111.44 Million by 2034, expanding at a CAGR of 2.47% during 2026-2034. This steady osmometers market growth reflects rising chronic disease diagnostics, expanding pharmaceutical quality control requirements, technological advancements in osmometry, and the growing footprint of diagnostic laboratories across global healthcare and life-sciences networks.
Osmometers Industry Overview
An osmometer is an analytical instrument used to measure the osmotic concentration, or osmolality, of a solution a critical parameter for assessing fluid balance, biological sample integrity, and pharmaceutical formulation quality. By leveraging freezing point depression, vapor pressure depression, or membrane-based measurement principles, osmometers deliver the accuracy and reproducibility that clinical laboratories and regulated manufacturing environments require for routine, high-volume testing.
Osmometers are deployed across a broad continuum of use cases:
- Clinical diagnostics: Evaluating hydration status, electrolyte imbalance, and renal concentrating function in serum and urine samples
- Pharmaceutical quality control: Osmolality testing of injectable formulations, parenteral solutions, and biologic drug products
- Biopharmaceutical R&D: Formulation development, process validation, and osmolality control for monoclonal antibodies and cell therapies
- Academic and polymer research: Number-average molecular weight determination and macromolecule characterization using membrane osmometry
- Point-of-care testing: Handheld and portable osmometers enabling bedside osmolality assessment in intensive care and emergency settings
Global Osmometers Market Size & Key Statistics
Below are the key osmometers market statistics drawn from IMARC Group's comprehensive market analysis:
|
Report Attribute |
Key Statistics |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Osmometers Market Size in 2025 |
USD 88.89 Million |
|
Market Forecast in 2034 |
USD 111.44 Million |
|
Market Growth Rate (2026-2034) |
2.47% CAGR |
|
Largest Region |
North America (36.7% share) |
|
Leading Product Type |
Freezing Point Osmometers (56.8% share) |
|
Leading Sampling Capacity |
Single-Sample Osmometers (61.5% share) |
Request for a Sample Report for Detailed Osmometers Market Share Evaluation: https://www.imarcgroup.com/osmometers-market/requestsample
Key Market Drivers & Osmometers Market Trends in 2026
Several powerful forces are shaping osmometers market trends and fuelling sustained growth expectations across global clinical and pharmaceutical laboratory markets:
1. Rising Prevalence of Chronic Diseases
Increasing incidence of chronic kidney disease, diabetes, and cardiovascular conditions globally is generating ever-expanding demand for routine osmolality testing. Osmometers — by virtue of their accuracy in evaluating hydration status and renal concentrating ability — sit at the centre of routine clinical laboratory workflows worldwide.
2. Pharmaceutical Quality Control Demand
Stringent pharmaceutical manufacturing regulations require osmolality testing of injectable formulations, parenteral solutions, and biologic drugs. The growing biologics pipeline and contract manufacturing expansion are increasing osmometer installations within quality control laboratories at pharmaceutical and biopharmaceutical manufacturing facilities worldwide.
3. Technological Advancements in Osmometry
Innovations in automated sample handling, touchscreen interfaces, digital connectivity, and miniaturized detection systems have enhanced osmometer usability and accuracy. New instrument generations reduce sample volume requirements, enable faster analysis, and facilitate seamless integration with laboratory information management systems across regulated environments.
4. Expanding Diagnostic Laboratory Networks
Rapid growth of hospital-based and independent diagnostic laboratories across emerging economies is creating new installation opportunities for clinical osmometers. Government healthcare spending increases and private laboratory network expansion across Asia-Pacific and Latin America are broadening the accessible Osmometers Market base significantly.
5. Laboratory Automation and High-Throughput Osmometry
Pharmaceutical and biotech laboratories are transitioning to automated multi-sample osmometers integrated with robotic sample handlers and LIMS platforms, enabling unattended batch processing and improved reproducibility across high-volume quality control workflows in regulated manufacturing environments.
6. Miniaturization and Point-of-Care Osmometry
Handheld and portable osmometer development is enabling bedside osmolality testing in intensive care and emergency settings. Reduced sample volume requirements and faster turnaround times are improving clinical decision-making for critically ill patients requiring rapid fluid management assessment.
7. Biologics-Driven Osmolality Demand Growth
The expanding biologics pipeline, encompassing monoclonal antibodies, vaccines, and cell therapies, requires precise osmolality control across formulation development and manufacturing. This trend is sustaining long-term multi-sample osmometer demand within pharmaceutical quality assurance and process development laboratories worldwide.
Key Market Segmentation
By Product Type
Freezing Point Osmometers — Largest Segment (56.8% share, 2025): These instruments dominate the product-type segment owing to their reliability, cost-effectiveness, and widespread adoption across clinical diagnostic and pharmaceutical quality control applications. Their compatibility with diverse aqueous sample matrices and established regulatory acceptance drive sustained dominance across global laboratory networks. Nova Biomedical and Precision Systems exemplify leading freezing point platforms.
Vapor Pressure Osmometers (28.4% share): These serve specialized research and pharmaceutical applications requiring non-aqueous or viscous sample analysis, measuring osmolality via dew point depression where freezing point measurement is impractical.
Membrane Osmometers (14.8% share): These address niche high-molecular-weight polymer and macromolecule characterization applications in academic research and advanced materials science laboratories.
By Sampling Capacity
Single-Sample Osmometers — Largest Segment (61.5% share, 2025): These dominate the sampling capacity segment, driven by established clinical diagnostic workflows and cost considerations across hospital and independent laboratory settings. Their widespread installed base and suitability for low-to-medium throughput applications reinforce continued leadership in this segment of the Osmometers Market globally.
Multi-Sample Osmometers (38.5% share): These are gaining rapid adoption in pharmaceutical quality control and high-volume biotech laboratories, growing at approximately 2.68% CAGR through 2034 as processing efficiency and automation integration demands rise across regulated manufacturing environments.
By Application
The report segments the market by application into Clinical, Pharmaceutical and Biotech, and Others. Clinical applications span hydration status assessment, electrolyte balance evaluation, and renal function testing, while pharmaceutical and biotech applications centre on formulation validation and quality control testing of injectable and biologic drug products.
By End User
End users covered in the report include Laboratory and Diagnostic Centers, Hospitals, and Others. Laboratory and diagnostic centers represent a significant share of installations, supported by routine clinical osmolality testing volumes, while hospitals maintain substantial osmometer deployment across emergency, inpatient, and outpatient care settings.
Regional Osmometers Market Analysis
|
Region |
Key Highlights |
|
North America — Largest (36.7%) |
United States & Canada; advanced healthcare and pharmaceutical infrastructure, high chronic disease diagnostics demand, FDA quality compliance requirements, dense installed base of leading osmometer manufacturers |
|
Europe (28.1%) |
Germany, France, UK, Italy, Spain, Russia; stringent EU MDR regulatory compliance, established pharmaceutical industry, hospital laboratory modernization programmes |
|
Asia-Pacific — Fastest Growing (24.2%) |
China, Japan, India, South Korea, Australia, Indonesia; expanding diagnostic laboratory networks, growing pharmaceutical manufacturing, rising chronic disease burden, government healthcare investment |
|
Latin America (6.1%) |
Brazil, Mexico; healthcare infrastructure development, growing private laboratory sector, pharmaceutical sector expansion |
|
Middle East & Africa (4.9%) |
UAE, Saudi Arabia, South Africa; hospital capacity expansion, increasing pharmaceutical manufacturing investment, government healthcare modernization programmes |
North America leads the global Osmometers Market Share, underpinned by its concentration of major pharmaceutical and biopharmaceutical manufacturers, comprehensive hospital networks, and significant investment in clinical diagnostic infrastructure. FDA quality system requirements mandate osmolality testing across parenteral drug manufacturing, sustaining consistent instrument demand.
Asia-Pacific represents the fastest-growing regional market, driven by expanding diagnostic laboratory networks, growing pharmaceutical manufacturing investment, and rising chronic disease burden across China, Japan, and India, alongside government healthcare infrastructure programmes broadening instrument accessibility.
Connect for Detailed Osmometers Market Share Segmentation Analysis — Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=5206&flag=C
Leading Players in the Global Osmometers Industry
The global osmometers market is moderately consolidated, with specialized analytical instrument manufacturers from North America and Europe collectively commanding significant market share. Key companies covered in the IMARC Group report include:
|
Company |
Key Products / Operations |
Market Position |
|
Nova Biomedical |
OsmoTECH XT, OsmoTECH PRO, OsmoTECH HT, OsmoPRO MAX, Osmo1 |
Leader — expanding automated osmometer portfolio and LIMS connectivity |
|
ARKRAY, Inc. |
OM-6070, OM-6060 |
Established — strengthening clinical diagnostic portfolio and Asia-Pacific distribution |
|
KNAUER Wissenschaftliche Geräte GmbH |
K-7400S |
Established — focused on high-precision research and polymer characterization |
|
Precision Systems, Inc. |
Multi-OSMETTE, OSMETTE A/II/III/XL series, MICRO-OSMETTE |
Established — strong North American clinical laboratory installed base |
|
Labtron Equipment Ltd. |
LOSM-A10, LOSM-A11 |
Emerging — cost-effective clinical/pharma/research osmometers |
Latest Osmometers Market Industry Developments
October 2025 — Nova Biomedical / Advanced Instruments
Advanced Instruments began operating under the Nova Biomedical name, creating a larger global life-sciences tools company focused on analytical instruments, consumables, and diagnostic solutions for the biopharmaceutical and clinical markets — reinforcing its osmometry market leadership position.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Healthcare, Technology, Chemicals, Energy, Food & Beverages, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Portuguese (Brazil)
 Greek