Microchip Manufacturing Plant Project Report 2026: Setup Cost and Financial Feasibility
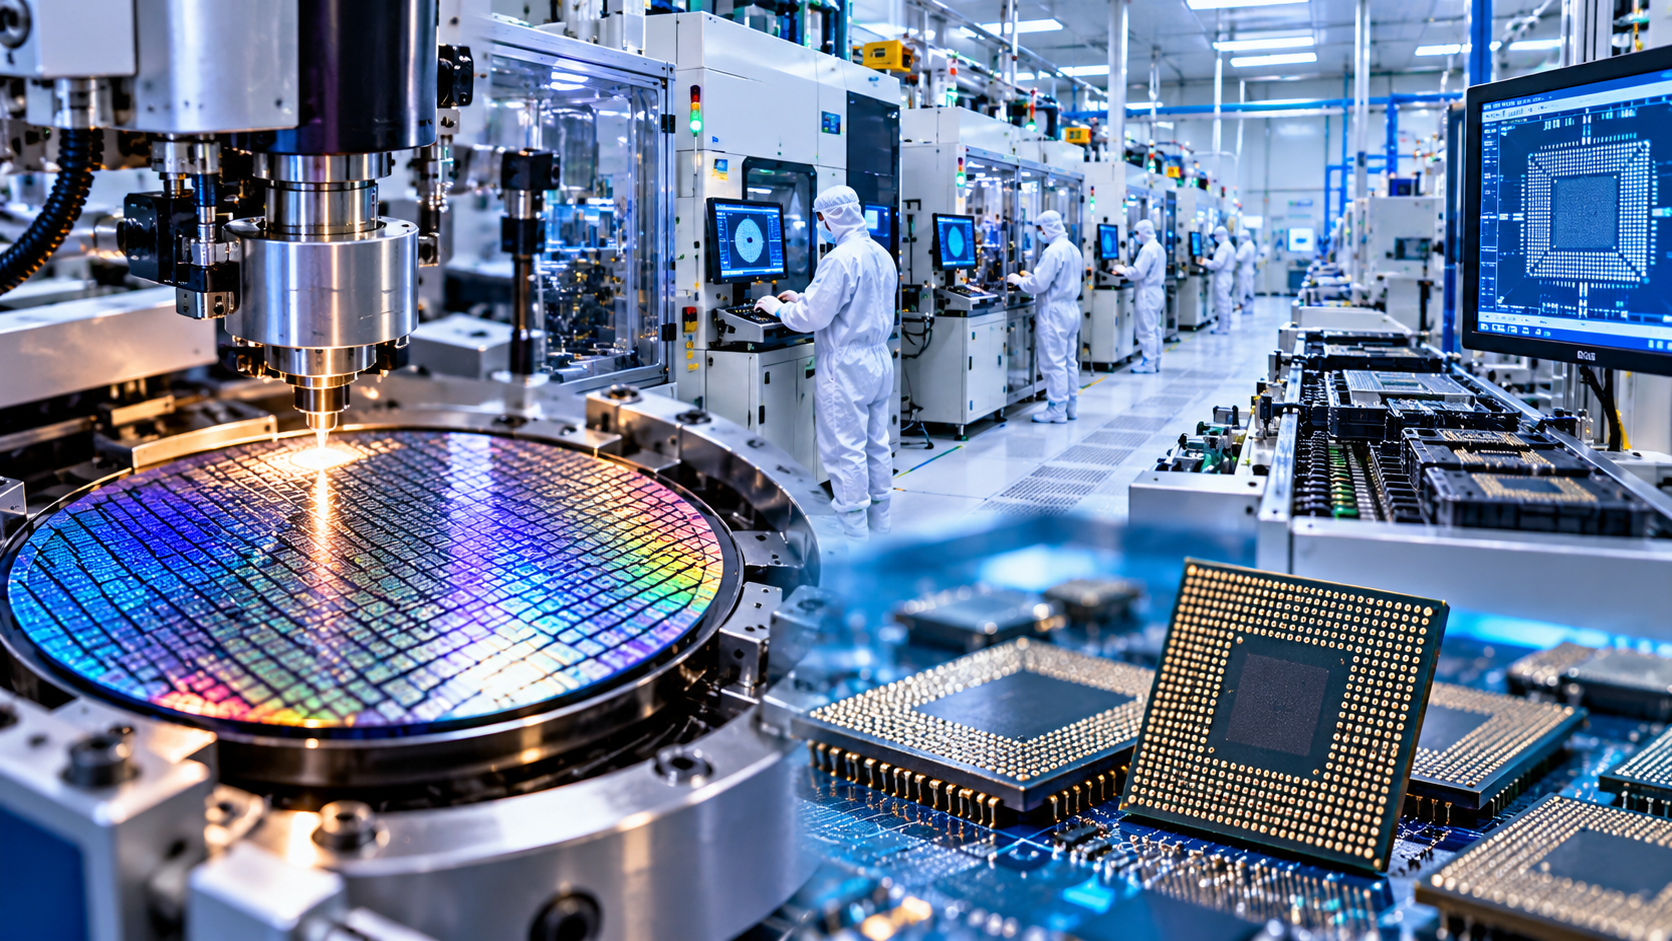
IMARC Group's comprehensive DPR report, "Microchip Manufacturing Plant Project Report 2026: Industry Trends, Plant Setup, Machinery, Raw Materials, Investment Opportunities, Cost and Revenue," provides a complete roadmap for setting up a microchip manufacturing plant cost. The microchip market is driven by rising demand for consumer electronics, expansion of data centers and cloud computing, growth in electric vehicles, increasing adoption of artificial intelligence technologies, and government initiatives supporting domestic semiconductor production. The global microchip market size was valued at USD 92.91 Billion in 2025 and is expected to reach USD 181.29 Billion by 2034, exhibiting a CAGR of 7.7% from 2026 to 2034.
This feasibility report covers a comprehensive market overview to micro-level information such as unit operations involved, raw material requirements, utility requirements, infrastructure requirements, machinery and technology requirements, manpower requirements, packaging requirements, and transportation requirements. The microchip manufacturing plant setup cost is provided in detail, covering project economics, capital investments (CapEx), project funding, operating expenses (OpEx), income and expenditure projections, fixed and variable costs, expected ROI, net present value (NPV), profit and loss account, and financial analysis.
Microchip Manufacturing Plant Project Report Summary:
- Comprehensive guide for setting up a microchip (integrated circuit) manufacturing plant.
- Covers global microchip market trends and industry outlook for 2026.
- Detailed project setup, including unit operations and fabrication processes.
- Raw material and utility requirements (silicon wafers, photoresists, specialty gases, chemicals).
- Infrastructure, cleanroom, and machinery specifications.
- Workforce and staffing requirements.
- Packaging and transportation details.
- Financial aspects: investment opportunities, cost analysis, and revenue projections.
In addition to covering operational aspects, the report offers detailed insights into the microchip manufacturing plant process and project economics:
- Detailed insights into the silicon wafer fabrication, photolithography, and IC packaging process.
- In-depth project economics and financial metrics.
- Covers capital investments (CapEx) and project funding.
- Analysis of operating expenses (OpEx) and income projections.
- Breakdown of fixed and variable costs, direct and indirect expenses.
- Evaluation of ROI (Return on Investment) and NPV (Net Present Value).
- Profit and Loss account analysis.
- Comprehensive financial analysis for decision-making.
- Provides a complete roadmap for successfully establishing a microchip manufacturing unit.
What is a Microchip?
A microchip, also known as an integrated circuit (IC), is a compact semiconductor device engineered on silicon wafers to build interconnected electronic components — including transistors, resistors, capacitors, and diodes — within an area often smaller than a human fingernail. These billions of transistors are interconnected by nano-scale metal interconnects to perform computing, control, memory, and signal processing functions in electronic systems with extraordinary speed and energy efficiency.
Microchips are the foundational building blocks of virtually all modern digital systems. They power the processors in smartphones and personal computers, the memory modules in data centers, the control units in electric vehicles, the sensors in industrial automation systems, the communication transceivers in 5G infrastructure, the diagnostic instruments in medical devices, and the guidance systems in aerospace and defense platforms. The development of nanometer-scale fabrication processes — progressing from 90nm to 65nm, 28nm, 7nm, 5nm, 3nm, and now approaching 2nm — continuously improves microchip performance while reducing power consumption and enabling denser transistor integration.
Microchips span a vast product spectrum. Logic chips (processors, FPGAs, ASICs) execute computational tasks. Memory chips (DRAM, NAND Flash) store and retrieve data. Power management ICs regulate voltage and current in electronic systems. Analog and mixed-signal chips interface between the physical world and digital systems. Microcontrollers combine processor, memory, and I/O in a single chip for embedded applications. The semiconductor industry reached approximately USD 697 billion in total revenue in 2025, with the microchip segment valued at USD 92.91 billion and growing at 7.7% CAGR through 2034 — making it one of the most strategically important manufacturing sectors on the planet.
Request for a Sample Report: https://www.imarcgroup.com/microchip-manufacturing-plant-project-report/requestsample
Major Applications
- Consumer Electronics: Used in smartphones, laptops, tablets, gaming consoles, smart TVs, wearables, and smart home products — the largest single end-use category by volume.
- Automotive Industry: Integrated into electric vehicles (powertrain control, battery management), advanced driver assistance systems (ADAS), LiDAR sensors, infotainment, and V2X communication units. Each EV contains 2-3x the semiconductor content of a conventional vehicle.
- Data Centers and Cloud Computing: Powers high-performance AI training and inference processors (GPUs, TPUs), server CPUs, DRAM memory modules, and high-bandwidth NAND flash storage. AI-specific chips market projected to exceed USD 200 billion by 2027.
- Telecommunications: Applied in 5G base station processors, RF front-end modules, routers, optical network chips, and satellite communication ICs.
- Industrial Automation: Supports robotics controllers, IoT sensors, PLC microcontrollers, edge AI inference chips, and smart manufacturing equipment.
- Aerospace and Defence: Radiation-hardened microchips for satellites, avionics, guided systems, electronic warfare, and secure communications equipment.
- Healthcare: Microchips power diagnostic instruments, implantable devices (pacemakers, cochlear implants), patient monitoring systems, and point-of-care genomic sequencers.
Why Invest in Microchip Manufacturing?
- Expanding Digital Infrastructure: Every digital transformation — AI, cloud, 5G, IoT, EV — directly and structurally increases chip demand. More than 1.2 billion people adopted AI tools within three years, exceeding the adoption speed of the internet and smartphones.
- Government Semiconductor Incentives: The US CHIPS and Science Act provides 25% investment tax credit on semiconductor equipment and construction. The EU Chips Act targets 20% of global chip production by 2030. India's Semcon India Programme committed INR 76,000 crore. Japan, South Korea, and Taiwan all offer substantial subsidies.
- High Entry Barriers Protect Long-Term Positioning: Advanced fabrication technology requires years of process R&D, OEM qualification, and talent development — creating powerful competitive moats that protect margins for established producers.
- Rapid Innovation Cycle Creates Value Opportunities: Each process node transition (e.g., 7nm to 5nm to 3nm) enables new chip architectures and applications, creating recurring revenue opportunities for manufacturers who invest in leading-edge capabilities.
- Strategic National Importance: Microchips are now classified as critical national infrastructure in the USA, EU, Japan, India, South Korea, and Taiwan. Government contracts, strategic reserves, and allied procurement frameworks support demand stability.
Market Trends and Drivers
The global microchip market is experiencing one of its most dynamic expansion phases in history, growing from USD 92.91 billion in 2025 and projected to reach USD 181.29 billion by 2034 at a CAGR of 7.7%. The broader semiconductor industry reached approximately USD 697 billion in 2025 — an 11.2% increase from 2024 — and is projected to hit USD 1 trillion by 2026 according to the Semiconductor Industry Association. These extraordinary growth trajectories are driven by an unprecedented convergence of transformative technology trends operating simultaneously.
Artificial intelligence is the single most powerful demand driver of this cycle. The AI Economy Institute's AI Diffusion Report confirms that more than 1.2 billion people began using AI tools within three years, outpacing internet and smartphone adoption rates. This demand is translating directly into surging orders for AI accelerator chips (GPUs, custom AI ASICs), high-bandwidth memory (HBM), and advanced packaging solutions. Semiconductor CapEx is responding in kind: TSMC projects 2026 CapEx of USD 52-56 billion (a 27-37% increase from 2025), GlobalFoundries plans a 70% CapEx increase in 2026, and the semiconductor industry is expected to start 18 new fab construction projects in 2025. Total industry CapEx in 2025 was USD 163 billion, with TSMC alone spending USD 40.9 billion.
Government-led supply chain reshoring is reshaping global fab geography. GlobalFoundries announced in June 2025 plans to invest USD 16 billion into semiconductor manufacturing expansion across New York and Vermont. The German government confirmed EUR 1 billion in support for Infineon's EUR 5 billion expanded fab in Dresden and EUR 495 million towards GlobalFoundries' EUR 1.1 billion fab expansion in Dresden. Elon Musk announced plans for Terrafab — a USD 20-25 billion wafer fab in Austin, Texas targeting 2nm process nodes with 1 million wafer starts per month capacity. India's Semiconductor Mission approved four additional fabs in 2025. The K500 Chip Testing Facility at Michigan State University opened in February 2026, receiving USD 14 million in federal funding to provide 6,000 testing hours annually for space, military, medical, and automotive chip reliability testing. The semiconductor industry simultaneously operates 167 fabs processing 300mm wafers and 224 fabs processing 200mm wafers globally, with 97 new high-volume fabs planned between 2023 and 2025.
Key Insights Covered in the Microchip Manufacturing Plant Report
Market Coverage
- Market Trends: Analysis of current and emerging trends — AI chip demand, chiplet architectures, advanced packaging (CoWoS, SoIC), EUV lithography adoption, and domestic reshoring investment waves.
- Market Segmentation: Breakdown by chip type (logic, memory, analog, mixed-signal, power), process node, wafer size (200mm, 300mm), end-use industry, and geography.
- Regional Analysis: Distribution across Taiwan (TSMC dominant), South Korea (Samsung, SK Hynix), USA (Intel, Micron, GlobalFoundries), China (SMIC), Europe (Infineon, STMicro), and emerging hubs (India, Japan).
- Price Analysis: Evaluation of silicon wafer pricing, photoresist and specialty gas cost trends, and the impact of node transitions on wafer fabrication cost per chip.
- Impact of Geopolitics: US-China trade restrictions, export controls on EUV equipment, allied-nation semiconductor investment pacts, and their impact on fab geography and supply chain resilience.
- Market Forecast: Outlook and projections through 2034, with CAGR of 7.7% and semiconductor industry approaching USD 1 trillion by 2026.
Key Aspects Required for Setting Up a Microchip Manufacturing Plant
Detailed Process Flow
- Product Overview: Comprehensive description of microchip product types — logic ICs (CPUs, ASICs, FPGAs), memory (DRAM, NAND), analog and mixed-signal ICs, power management ICs, microcontrollers, and sensor ICs — with process node specifications and applicable quality standards (JEDEC, IPC, MIL-STD).
- Unit Operations Involved: Silicon wafer procurement and incoming inspection — Thermal oxidation (SiO2 gate formation) — Chemical vapour deposition (CVD) of dielectric and polysilicon layers — Photolithography (pattern transfer using EUV or DUV exposure tools) — Etching (dry RIE plasma etch or wet chemical etch) — Ion implantation (dopant introduction for p/n junctions) — Chemical Mechanical Polishing (CMP for planarization) — Physical vapour deposition (PVD) for metal interconnect layers — Electrochemical deposition (ECD) for copper interconnects — Wafer metrology and in-line inspection — Backend metallization and passivation — Wafer electrical testing (probe card testing) — Wafer dicing (laser or blade saw) — Die attachment and wire bonding or flip-chip bumping — Moulding and encapsulation — Package-level testing — Final burn-in, marking, and shipment.
- Mass Balance and Raw Material Requirements: A single 300mm silicon wafer yields 200-3,000 individual dies depending on die size and process complexity. Key inputs per 300mm wafer start: one polished silicon wafer (USD 150-500 depending on grade), photoresists and mask sets, 20-40 specialty gases (silane, nitrogen trifluoride, argon, hydrogen), deionised ultra-pure water (1,500-3,000 litres per wafer start for advanced nodes), and chemical slurries (CMP polishing). Yield rates range from approximately 50-60% at process node introduction to 85-95% at mature node production.
- Quality Assurance Criteria: SEMI standards (M1, M12, C8 for silicon wafers), JEDEC JESD47 (stress test qualification for ICs), AEC-Q100 (automotive IC qualification), MIL-STD-883 (military ICs), ISO 26262 (automotive functional safety), IPC-A-610 (acceptability of electronic assemblies), and ISO 9001 quality management.
- Technical Tests: In-line metrology (critical dimension SEM, overlay measurement, film thickness by ellipsometry), wafer-level electrical testing (probe station, parametric testing), reliability testing (HTOL high-temperature operating life, HAST humidity and autoclave stress, ESD testing), burn-in screening, and final outgoing quality inspection (AQL sampling).
Project Details, Requirements, and Costs Involved
- Land, Location, and Site Development: Assessment of land requirements (typically 50-500+ acres depending on fab scale), access to ultra-pure water supply (critical — advanced fabs consume 2-10 million gallons per day), stable and redundant high-voltage power supply (advanced fabs consume 100-500 MW continuously), and proximity to skilled semiconductor workforce. Seismically stable locations are preferred to protect nanometer-precision equipment. Sites within semiconductor clusters (Silicon Valley, Taiwan Hsinchu, South Korea Gyeonggi, Dresden, Japan Kumamoto) provide ecosystem advantages. Land and site development typically represents 2-5% of total CapEx.
- Plant Layout: Cleanroom design is the central engineering challenge. Advanced logic fabs (sub-7nm) require ISO Class 1-3 cleanrooms (less than 10 particles per cubic metre). The layout covers: wafer receiving and outgoing inspection area, cleanroom fab floor (bay-and-chase design with overhead transport systems), photolithography bay (vibration-isolated, temperature and humidity controlled to 0.01 degrees C), metrology and inspection rooms, wet chemistry etch and clean stations, thermal processing furnaces, ion implanter bay, CMP station, packaging and test area, and utility infrastructure (ultra-pure water plant, exhaust gas treatment, chemical storage and distribution, power conditioning).
- Machinery Requirements and Costs: Key equipment includes EUV or DUV photolithography scanners (ASML TWINSCAN NXE — USD 150-350 million each for EUV), plasma etch systems, CVD/ALD deposition tools, ion implanters, CMP systems, PVD metallization tools, automated wafer inspection systems (KLA, Applied Materials), wafer probe testers, and back-end packaging equipment. Equipment represents 60-75% of total fab CapEx. Machinery costs account for the largest portion of the total capital expenditure.
- Raw Material Requirements and Costs: Primary inputs include silicon wafers (35-45% of OpEx), photoresists and photomask sets (significant cost, especially EUV masks at USD 500K-1M each), specialty gases (NF3, SiH4, H2, N2, Ar, HCl — 20-40 gas types), chemical slurries for CMP, wet chemistry for cleaning and etching (HF, H2SO4, H2O2, NH4OH), and deionised ultra-pure water. Long-term supply contracts with qualified suppliers are essential; a lack of even one specialty chemical can reduce fab output by 10-20%.
- Packaging Requirements and Costs: Finished microchips are packaged in moisture-barrier trays, tape-and-reel (for SMT production), or waffle-pack carriers. Shipping containers are ESD-protective, temperature-controlled, and tracked with chain-of-custody documentation. High-value chips (AI accelerators, advanced CPUs) may require special handling and temperature-controlled air freight.
- Utility Requirements and Costs: Utilities constitute 25-35% of total OpEx — the second largest cost category. A 300mm fab at full capacity consumes 100-500 MW of electricity continuously (equivalent to a small city), 2-10 million gallons of ultra-pure water per day, large volumes of bulk gases (nitrogen, oxygen, argon), and generates significant chemical waste requiring treatment. Renewable energy procurement is increasingly critical for ESG compliance and cost management.
- Human Resource Requirements and Costs: Process engineers (photolithography, etch, deposition, CMP), equipment engineers, yield engineers, quality reliability engineers, metrology technicians, cleanroom operators, software and automation engineers, supply chain managers, EHS specialists, and plant management. A 300mm fab with 20,000 wafer starts per month requires approximately 1,500-3,000 FTEs. Leading-edge node fabs require deep expertise that takes years to develop — talent is a critical constraint and competitive differentiator.
Plant Setup Cost and Profit Analysis
Microchip manufacturing represents the most capital-intensive manufacturing sector in the world. The following framework covers investment requirements across the full spectrum — from legacy-node specialty fabs accessible to mid-size manufacturers to leading-edge fabs operated only by the world's largest semiconductor companies. The reference financial model is based on a mature-node 200mm fab (130nm-65nm process, primarily for automotive, industrial, power management, and analog ICs) with a capacity of 50,000 wafer starts per month.
Ask an Analyst: https://www.imarcgroup.com/request?type=report&id=45413&flag=C
Project Economics
- Capital Investments: Initial costs for land, cleanroom design and construction, photolithography systems, etch and deposition tools, ion implanters, CMP systems, wafer inspection equipment, backend packaging lines, ultra-pure water plant, power infrastructure, and EHS systems. Equipment represents 60-75% of total CapEx — the dominant investment category.
- Operating Costs: Recurring expenses dominated by silicon wafers (35-45% of OpEx) and utilities especially electricity at 25-35% of OpEx; plus photoresists, specialty gases, chemical slurries, labour for 1,500-3,000+ FTEs, equipment maintenance, QC and reliability testing, and regulatory compliance.
- Expenditure Projections: Detailed forecasts accounting for silicon wafer price trends, specialty gas availability and pricing, electricity tariff changes, equipment consumable costs, capacity ramp-up from Year 1 (55% utilisation) to stabilised Year 5+ (90%+ utilisation).
- Revenue Projections: Expected income from automotive ICs, power management chips, microcontrollers, analog ICs, RF chips, and potential AI accelerator products — each priced per wafer start based on node complexity.
- Taxation and Depreciation: Analysis of CHIPS Act investment tax credits (25% in USA), EU Chips Act state aid, India Semcon incentives, accelerated depreciation on semiconductor equipment (7-10 year schedule), and R&D tax credits.
- Profit Projections: Estimated profitability by year reflecting fab ramp-up trajectory (1.5-2 years to volume production from construction completion), yield improvement curves, and product mix evolution toward higher-margin advanced products.
- Financial Analysis: Comprehensive evaluation including NPV, IRR, ROI, DSCR, break-even capacity utilisation (critical threshold: 90%+), sensitivity analysis (wafer pricing, yield, energy cost, utilisation rate), and 15-year cash flow modelling — essential for project financing discussions.
Customisation Options Available
- Plant Location: Selection of optimal site based on semiconductor ecosystem proximity, skilled workforce availability, utility infrastructure (power and water), government incentive eligibility (CHIPS Act, EU Chips Act, India Semcon), and seismic stability. Arizona, Texas, Ohio, Germany, Japan, and India are current major greenfield investment destinations.
- Plant Capacity: Customisation from 5,000 WSPM specialty pilot fabs to 200,000+ WSPM mega-fab complexes.
- Wafer Size and Process Node: Configuration for 150mm (specialty analog, power), 200mm (mature technology, automotive, industrial), or 300mm (leading-edge logic, memory, advanced packaging) fabs at the appropriate process node (250nm down to 2nm).
- Product Focus: Logic chips (CPUs, ASICs, FPGAs), memory (DRAM, NAND), analog and power management, RF and wireless, automotive-grade (AEC-Q100), or advanced AI accelerator chips — each with distinct process flows and qualification requirements.
- Business Model: Integrated Device Manufacturer (IDM — own design and manufacturing), pure-play foundry (contract manufacturing for fabless customers), or fab-lite (selective manufacturing of certain product lines).
- List of Machinery Providers: Key equipment suppliers include ASML (lithography), Applied Materials (CVD, etch, CMP, inspection), Lam Research (etch, deposition), KLA Corporation (inspection, metrology), Tokyo Electron (CVD, coaters), and Onto Innovation (metrology).
Key Questions Addressed in This Report
- How has the global microchip market performed so far and how will it perform in the coming years?
- What is the market segmentation of the global microchip market by chip type, process node, end-use, and geography?
- What is the regional breakup of the global microchip market and where are new fab investments being made?
- What are the price trends of key raw materials — silicon wafers, photoresists, specialty gases — in the microchip industry?
- What is the structure of the global microchip manufacturing industry and who are the key players?
- What are the various unit operations involved in a microchip manufacturing plant?
- What is the total land, cleanroom area, and infrastructure required for different fab scales?
- What are the machinery requirements — including photolithography, etch, and deposition — and their associated capital costs?
- What are the raw material requirements, supply chain risks, and procurement strategies?
- What is the total investment required and what are the expected ROI and payback period by fab scale?
- What are the operating costs and what are the critical levers — especially fab utilisation — for profitability?
- What government subsidies, CHIPS Act credits, and strategic financing are available for microchip manufacturing projects?
- What certifications, safety protocols, environmental compliance, and quality standards are required?
- What are the key success and risk factors in the microchip manufacturing industry?
How IMARC Can Help?
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Services
- Plant Setup
- Factory Auditing
- Regulatory Approvals and Licensing
- Company Incorporation
- Incubation Services
- Recruitment Services
- Marketing and Sales
Customisation Options:
- Plant Location: Selection of optimal location (country/region) for the plant.
- Plant Capacity: Customisation based on desired wafer capacity and process node.
- Machinery: Equipment selection for specific node requirements and production scale.
- Any Additions: Additional scope such as advanced packaging, testing services, or specific product focus.
Contact Us:
IMARC Group
134 N 4th St. Brooklyn, NY 11249, USA
Email: [email protected]
Tel No:(D) +91 120 433 0800
United States: (+1-201971-6302)

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Greek