Copper Pipes and Tubes Market Outlook 2026-2034: Size, Share, Trends, Demand and Forecast
Copper Pipes and Tubes Market Overview
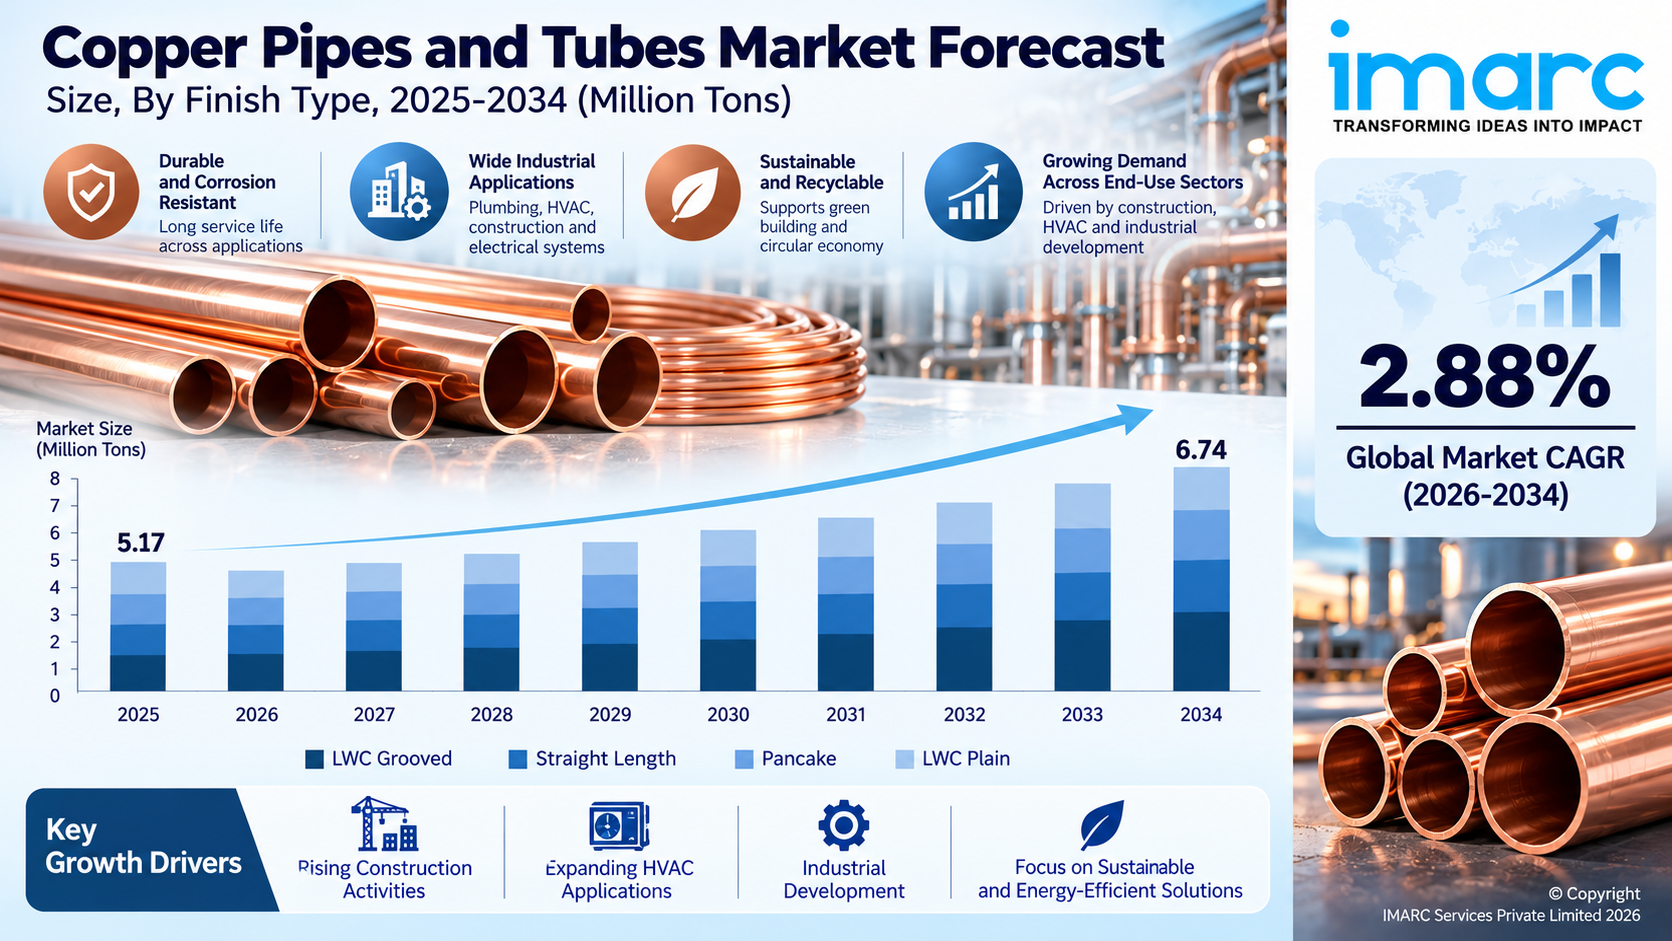
The global copper pipes and tubes market share is experiencing steady growth as demand increases across construction, plumbing, heating, ventilation, air conditioning (HVAC), refrigeration, and industrial applications. The market reached 5.17 Million Tons in 2025 and is projected to reach 6.74 Million Tons by 2034, expanding at a CAGR of 2.88% during 2026–2034. Asia Pacific dominated the market in 2025, accounting for 75.4% of the global market share.
The industry is being influenced by rapid urbanization, expanding construction activities, rising demand for energy-efficient cooling systems, and growing investments in water distribution and industrial infrastructure. Copper's durability, corrosion resistance, thermal conductivity, and recyclability are further strengthening its position across residential, commercial, and industrial applications.
Request a Sample Report for Detailed Evaluation: https://www.imarcgroup.com/copper-pipes-tubes-market/requestsample
What Is Driving Copper Pipes and Tubes Market Growth?
Expansion of Construction and Infrastructure Development
Rapid expansion in residential, commercial, and industrial construction is a major factor supporting the growth of the copper pipes and tubes market. Copper piping is widely used in plumbing, water distribution, heating systems, and building services because of its durability, corrosion resistance, long service life, and ability to withstand varying pressure and temperature conditions.
Increasing urbanization, population growth, and infrastructure investments are creating sustained demand for reliable piping materials across housing projects, office complexes, healthcare facilities, and public infrastructure. Copper's established role in modern plumbing systems makes it an important material for both new construction and building renovation.
Reflecting this momentum, Saudi Arabia announced the launch of the USD 26 Billion New Dammam seaside residential development in 2026. The project is planned to include more than 15,000 housing plots, commercial zones, parks, and waterfront residences designed to accommodate over 180,000 residents.
Developments of this scale increase requirements for plumbing, sanitation, and building service systems, supporting demand for copper pipes and tubes in modern construction projects. As infrastructure development continues across emerging and developed economies, copper piping is expected to remain an important component of residential and commercial building systems.
Growing Demand from Water Distribution and Plumbing Systems
Increasing investment in water supply and distribution infrastructure is strengthening demand for durable piping materials, contributing to the expansion of the copper pipes and tubes market.
Copper pipes are used in potable water systems because of their structural strength, corrosion resistance, and long service life. Their ability to withstand different operating pressures and temperatures makes them suitable for residential buildings, hotels, hospitals, and institutional facilities.
Modern plumbing systems increasingly emphasize reliability, durability, and long-term performance. These requirements support the use of copper pipes in applications where dependable water distribution and efficient building operations are essential.
According to the supplied market information, China planned to invest more than 5.4 Trillion Yuan, equivalent to approximately USD 756.9 Billion, in water conservancy infrastructure under the 14th Five-Year Plan covering 2021–2025. The initiative included reservoirs, irrigation systems, water diversion projects, and extensive dike networks.
Large-scale investments in water infrastructure increase the need for reliable distribution systems and related building services. These developments support demand for copper pipes and tubes used in plumbing and water management applications, alongside other suitable piping materials.
Increasing Emphasis on Copper Recycling and Resource Efficiency
The growing focus on copper recycling and resource efficiency is influencing the copper pipes and tubes market by strengthening the availability of secondary raw materials. Recycled copper can provide an additional source of feedstock for manufacturers while helping reduce waste and improve material utilization.
Copper's recyclability makes it suitable for applications in which material recovery and reuse are important considerations. Recycling also offers manufacturers opportunities to diversify raw material sourcing as demand increases across construction, HVAC, refrigeration, and industrial sectors.
Reflecting this trend, Hindalco Industries announced an investment of INR 2,450 Crore in Gujarat in 2024, including plans for India's first copper and e-waste recycling plant at Dahej. The facility was designed to process 300 to 350 kilotons of scrap annually.
The company's broader plans also included expanding copper smelting capacity at Dahej and developing a copper tube manufacturing unit in Vadodara to serve air conditioning and refrigeration applications.
These initiatives highlight the growing importance of integrated copper production, recycling, and downstream manufacturing. Improved material recovery and expanded processing capacity can help support the supply chain serving manufacturers of copper pipes and tubes.
Copper Pipes and Tubes Market Trends to Watch
Three major trends are shaping the development of the global copper pipes and tubes industry.
Infrastructure-led demand: Investments in residential construction, commercial buildings, water distribution, and public infrastructure are increasing the need for durable piping materials. Copper remains an important option for plumbing, heating, and building service applications because of its strength and long service life.
Energy-efficient cooling technologies: Growing demand for air conditioning, refrigeration, and heat pump systems is supporting copper tubing consumption. Copper's high thermal conductivity and reliability make it a widely used material in heat exchangers, condenser units, evaporator coils, and refrigerant lines.
Recycling and resource efficiency: Manufacturers are increasingly exploring recycled copper and improved material recovery to support resource efficiency and diversify feedstock supplies. Investments in recycling infrastructure and downstream manufacturing can strengthen the copper value chain.
Technological improvements in tube manufacturing are also creating opportunities for specialized products. Internally grooved copper tubes, precision-drawn tubing, and compact coil designs can improve heat transfer performance and support efficient equipment configurations.
As demand for cooling systems, modern plumbing, and industrial heat exchange equipment continues to evolve, manufacturers are focusing on product performance, manufacturing efficiency, and application-specific solutions.
Copper Pipes and Tubes Market Segmentation
The global copper pipes and tubes market is analyzed by finish type, outer diameter, and end-user, with each segment reflecting different technical requirements and industrial applications.
By Finish Type
-
LWC Grooved
-
Straight Length
-
Pancake
-
LWC Plain
LWC grooved tubes accounted for approximately 32.0% of the market share, making them the leading finish type segment in 2025.
Light wall coil tubes with internal helical grooves are designed to improve heat transfer by promoting turbulence in refrigerant flow. This design can enhance thermal performance while supporting compact equipment configurations and efficient use of material.
LWC grooved tubes are widely used in the manufacturing of split air conditioners, heat pumps, and commercial chillers. Their coil format also offers practical installation advantages, allowing easier handling, transportation, and bending during system assembly.
The flexible structure helps installers route tubing through confined spaces while maintaining the required performance characteristics. These advantages make LWC grooved tubes suitable for HVAC and refrigeration applications where thermal efficiency and compact designs are important.
The segment is expected to benefit from continued demand for energy-efficient cooling technologies and modern heat exchange systems.
By Outer Diameter
-
3/8, 1/2, and 5/8 Inch
-
3/4, 7/8, and 1 Inch
-
Above 1 Inch
The 3/8, 1/2, and 5/8 inch segment accounted for approximately 45.0% of the market in 2025, representing the leading outer diameter category.
Small-diameter copper tubes in these sizes are widely used in residential and light commercial HVAC systems, refrigeration equipment, and fluid distribution applications. Their popularity is supported by compatibility with standard connections used in split air conditioners, mini-split systems, and other compact cooling equipment.
These dimensions allow manufacturers to design efficient refrigerant circulation systems while controlling material requirements and simplifying installation. Their relatively compact cross-sections also support bending, handling, transportation, and integration into space-constrained equipment.
As demand for residential air conditioning and energy-efficient HVAC installations increases, small-diameter copper tubes remain an important component of the cooling equipment supply chain.
The segment's performance is closely connected to the expansion of air conditioning systems, refrigeration equipment, and other applications requiring reliable thermal management.
By End-User
-
HVAC
-
Industrial Heat Exchanger
-
Plumbing
-
Electrical
-
Others
HVAC dominated the end-user segment in 2025, accounting for approximately 44.0% of the market. Copper's high thermal conductivity, corrosion resistance, durability, and ability to withstand operating pressures make it a widely used material in heating, ventilation, air conditioning, and refrigeration systems.
Copper tubing forms a critical component of heat exchangers, condenser units, evaporator coils, and refrigerant line sets used in residential, commercial, and industrial cooling equipment.
The shift toward energy-efficient air conditioning technologies is also encouraging manufacturers to adopt tube designs that improve heat transfer and equipment performance.
According to the supplied report, India's HVAC market is projected to expand at a CAGR of 14.89% during 2026–2034. Increasing cooling requirements across residential buildings, commercial spaces, and industrial facilities are expected to support demand for copper pipes and tubes used in refrigeration and climate control systems.
Other end-user segments, including industrial heat exchangers, plumbing, and electrical applications, also contribute to demand by using copper's thermal and electrical properties in different equipment and infrastructure systems.
Regional Copper Pipes and Tubes Market Outlook
Asia Pacific
Asia Pacific dominated the global copper pipes and tubes market in 2025, accounting for 75.4% of the market share. The region's leading position is supported by its extensive manufacturing base, competitive production costs, established copper processing capabilities, and strong demand from construction, HVAC, and refrigeration industries.
China and India are particularly important markets because of their large industrial bases, expanding urban populations, and ongoing infrastructure development. Rising temperatures and growing adoption of air conditioning systems are further strengthening demand for copper tubing.
The region is also investing in domestic manufacturing capacity and industry standards to improve product quality and support long-term competitiveness.
Reflecting these efforts, BIS Chennai organized a Manak Manthan stakeholder consultation in 2025 to review a draft revised Indian standard for wrought copper tubes used in refrigeration and air conditioning. The consultation involved manufacturers, laboratories, industry bodies, and academic experts and sought feedback on proposed updates to IS 10773.
Such initiatives support collaboration across the manufacturing ecosystem and help align product standards with evolving technical requirements. Combined with infrastructure development and expanding HVAC production, these factors reinforce Asia Pacific's position in the global copper pipes and tubes market.
North America
North America represents an established market for copper pipes and tubes, supported by building standards, HVAC replacement cycles, industrial demand, and investment in modern infrastructure.
The United States remains a significant market because copper tubing is widely used in residential plumbing, commercial HVAC systems, refrigeration equipment, and industrial heat exchangers. Renovation of existing buildings and modernization of water distribution and heating systems continue to support demand for durable piping materials.
Manufacturing investments are also strengthening domestic production capabilities for specialized copper products used in cooling and industrial applications.
Reflecting this trend, Wieland announced a USD 27 Million investment in 2024 to expand its copper manufacturing facility in Pine Hall, North Carolina. The expansion was expected to create 50 new jobs and introduce new production lines for Tech Tubes and Cold Plates used in HVAC systems, electronics cooling, aerospace, and defense applications.
In a separate development, Wieland broke ground in 2025 on a USD 500 Million modernization project at its East Alton, Illinois facility. The project includes a new hot rolling mill designed to expand copper and copper alloy manufacturing capacity and improve production efficiency.
These investments illustrate the importance of domestic manufacturing and advanced production capabilities in meeting demand for specialized copper products across construction, cooling, and industrial sectors.
Canada also contributes to regional demand through residential construction, commercial infrastructure, and upgrades to building systems. As North American markets continue to emphasize reliable piping and energy-efficient equipment, copper pipes and tubes remain important materials across multiple applications.
Europe
Europe's copper pipes and tubes market is supported by energy-efficiency requirements, building modernization, and the growing adoption of heat pumps and low-carbon heating technologies.
Renovation programs across European countries are encouraging upgrades to existing buildings, including improvements to heating systems, water distribution networks, and HVAC infrastructure. These developments support demand for durable piping materials that can operate reliably across a range of pressure and temperature conditions.
Copper tubing is used in plumbing, heating, cooling, and heat exchange systems, making it relevant to both new construction and renovation projects.
Reflecting the scale of infrastructure activity, the UK government released an updated Infrastructure Pipeline in 2026 outlining 734 projects valued at approximately £718 Billion in planned public and private investment over the following decade.
Such infrastructure initiatives create opportunities for suppliers of construction materials, plumbing systems, and industrial components. Continued investment in building efficiency and modern infrastructure is expected to sustain demand for copper pipes and tubes across European markets.
Latin America
Latin America holds an important position in the global copper value chain because of its substantial copper resources and established mining industry. These resources support raw material availability for downstream manufacturing and contribute to international copper supply.
Chile is particularly significant in this context. According to the United States Geological Survey figures cited in the supplied report, Chile accounted for approximately 24% of global copper production in 2024, making it the world's largest copper producer.
The region also benefits from demand associated with construction, refrigeration, plumbing, and HVAC applications. Brazil and Mexico represent important markets where urban development, commercial infrastructure, and industrial activity support the consumption of copper-based products.
As construction and cooling requirements evolve, regional opportunities depend on the development of downstream processing capabilities, access to raw materials, and demand from end-use industries.
Middle East and Africa
The Middle East and Africa region is emerging as an important market for copper pipes and tubes, supported by infrastructure development, construction activity, and demand for cooling systems in hot climatic conditions.
Residential developments, commercial buildings, hospitality projects, and industrial facilities require reliable plumbing and HVAC installations. Copper tubing is widely used in these applications because of its thermal conductivity, durability, and ability to withstand demanding operating conditions.
The Gulf region is particularly important because of its expanding real estate sector and substantial investment in modern infrastructure.
According to the supplied report, total real estate transactions across Dubai, Abu Dhabi, Sharjah, and Ajman reached approximately AED 893 Billion by the end of 2024.
Large-scale property development supports demand for plumbing and climate control systems, creating opportunities for suppliers of copper pipes and tubes. Continued investment in residential, commercial, and hospitality infrastructure is expected to contribute to regional market development.
Competitive Landscape
The global copper pipes and tubes market features large integrated producers and specialized regional manufacturers competing across finish type, outer diameter, and end-user segments.
Companies compete through manufacturing scale, product quality, technological innovation, vertical integration, and the ability to supply application-specific tubing. Investments in precision tube drawing, internally grooved tubing, and advanced manufacturing processes help producers meet the technical requirements of modern HVAC and refrigeration equipment.
Capacity expansion in high-growth regions is another important strategy. Manufacturers are investing in new production lines, recycling facilities, and downstream processing capabilities to strengthen supply chains and respond to changing customer requirements.
Sustainability is also influencing competitive strategies. The use of recycled copper, improved resource efficiency, and manufacturing process optimization can help companies address environmental considerations while supporting long-term material availability.
Long-term supply relationships with HVAC original equipment manufacturers, plumbing distributors, and industrial customers can further strengthen market positioning.
Major companies identified in the global copper pipes and tubes market include:
-
Furukawa Electric Co., Ltd.
-
KME Germany GmbH
-
Kobe Steel, Ltd.
-
Luvata (Mitsubishi Materials Corporation)
-
MetTube Sdn Bhd
-
Mueller Industries Inc.
-
KMCT Corporation
-
Cerro Flow Products LLC
-
Golden Dragon Precise Copper Tube Group Inc.
-
Mehta Tubes Limited
-
Qingdao Hongtai Metal Co., Ltd.
-
Shanghai Hailiang Copper Tubes Co., Ltd.
Recent Industry Developments
February 2026: Lawton Tubes began construction of a £20 Million headquarters and manufacturing facility in Coventry to expand production capacity and meet demand for copper products. The solar-powered site is planned to include manufacturing space, large-scale warehousing, and automated technologies to improve operational efficiency. The expansion is intended to serve sectors such as construction, renewable energy, data centers, and national infrastructure.
October 2025: JTL Industries announced the launch of Continuous Cast (CC) Copper as part of its expansion into the non-ferrous metals segment. The company planned to increase monthly production from approximately 100 metric tons to 200 metric tons initially, with a target of 500 metric tons by the end of the fourth quarter. The product is intended for applications in electric vehicles, renewable energy systems, and infrastructure components.
Where Are the Biggest Copper Pipes and Tubes Market Opportunities?
The global copper pipes and tubes industry presents opportunities across several areas:
-
Construction and infrastructure: Residential developments, commercial buildings, and public infrastructure projects require durable piping for plumbing and building services.
-
HVAC and refrigeration: Rising cooling requirements and the adoption of energy-efficient air conditioning systems support demand for copper tubing and heat exchange components.
-
Water distribution systems: Investments in water supply, sanitation, and plumbing infrastructure create opportunities for reliable piping solutions.
-
Recycling and resource efficiency: Copper recovery and recycling can provide additional raw material supplies and support more efficient resource utilization.
-
Advanced manufacturing: Precision-drawn tubes, internally grooved products, and specialized copper components can serve evolving industrial and cooling requirements.
-
Emerging-market expansion: Rapid urbanization and industrial development across Asia Pacific and other developing regions create opportunities for manufacturers and suppliers.
-
Renewable energy and electrification: Investment in energy infrastructure and industrial equipment can increase demand for copper components in thermal management and related applications.
-
Domestic production capacity: New manufacturing facilities and modernization projects can strengthen supply chains and improve access to specialized copper products.
These opportunities are particularly relevant as industries seek materials that combine durability, thermal performance, reliability, and recyclability. Manufacturers that align production capabilities with changing construction, cooling, and industrial requirements can strengthen their competitive positioning.
Get Detailed Copper Pipes and Tubes Market Intelligence
The headline market figures provide a useful overview of industry development, but businesses evaluating manufacturing investments, market entry, product development, competitive positioning, or regional expansion may require more detailed market intelligence.
A comprehensive copper pipes and tubes market report can help businesses assess:
-
Market size and volume forecasts
-
Finish-type segmentation
-
Outer-diameter analysis
-
End-user market assessment
-
Regional and country-level market performance
-
Market drivers and emerging trends
-
Competitive landscape and company profiles
-
Construction and infrastructure demand
-
HVAC and refrigeration applications
-
Recycling and raw material developments
-
Manufacturing investments and industry developments
Detailed market intelligence can support strategic decisions involving production capacity, product portfolios, supply chain development, and expansion into high-potential end-use industries.
Request a Sample Report: https://www.imarcgroup.com/copper-pipes-tubes-market/requestsample
Copper Pipes and Tubes Market FAQs
What is the current size of the global copper pipes and tubes market?
The global copper pipes and tubes market reached 5.17 Million Tons in 2025 and is projected to reach 6.74 Million Tons by 2034.
What is the expected CAGR of the copper pipes and tubes market?
The market is projected to expand at a CAGR of 2.88% during 2026–2034.
Which region leads the copper pipes and tubes market?
Asia Pacific led the global market in 2025, accounting for 75.4% of the market share. Its large manufacturing base, infrastructure development, and demand for HVAC and refrigeration systems support its leading position.
Which finish type dominates the copper pipes and tubes market?
LWC grooved tubes represented the largest finish type segment in 2025, accounting for approximately 32.0% of the market share. Their heat transfer characteristics and suitability for HVAC and refrigeration systems support demand.
Which outer diameter segment holds the largest market share?
The 3/8, 1/2, and 5/8 inch segment led the outer diameter category in 2025, accounting for approximately 45.0% of the market. These sizes are widely used in residential and light commercial air conditioning and refrigeration systems.
Which end-user segment dominates the copper pipes and tubes market?
HVAC was the leading end-user segment in 2025, accounting for approximately 44.0% of the market share. Demand is supported by the use of copper tubing in heat exchangers, condenser units, evaporator coils, and refrigerant line sets.
What are the major trends in the copper pipes and tubes market?
Key trends include infrastructure development, rising HVAC and refrigeration demand, energy-efficient cooling technologies, copper recycling, resource efficiency, and investment in advanced tube manufacturing.
Conclusion
The global copper pipes and tubes market is evolving as demand grows across construction, plumbing, HVAC, refrigeration, and industrial applications. The market reached 5.17 Million Tons in 2025 and is projected to reach 6.74 Million Tons by 2034, registering a CAGR of 2.88% during 2026–2034.
Asia Pacific maintains its leading position because of its extensive manufacturing base, expanding infrastructure, and strong demand for cooling systems. Meanwhile, investments in construction, water distribution, copper recycling, and advanced manufacturing are creating opportunities across other regions and end-use industries.
Companies that focus on production efficiency, product innovation, supply chain resilience, and evolving customer requirements can strengthen their competitive positioning in the global copper pipes and tubes industry.
About the Author
IMARC Group is a global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers market intelligence across sectors including energy and mining, construction and manufacturing, automotive, chemicals and materials, hospitality, and more.
Media & Sales Contact
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Greek